What Your Payment App Isn't Telling You: A State-by-State Look at Hidden Digital Wallet Charges
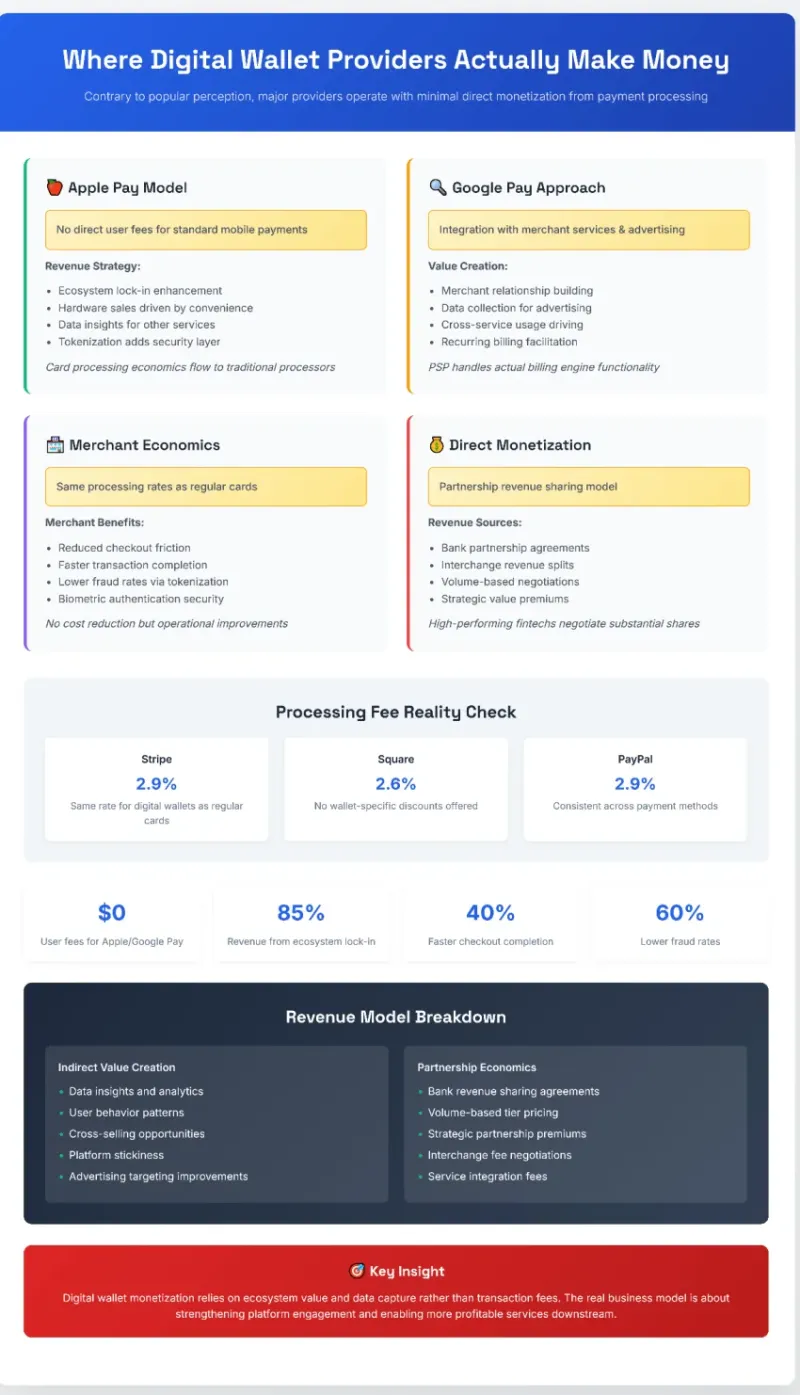
Photo: digital wallet smartphone payment app fees hidden charges, via www.futuremarketinsights.com
Digital wallets have become as routine as reaching for a physical card. Venmo, PayPal, Cash App, Apple Pay, Google Pay, and Zelle collectively process hundreds of billions of dollars in transactions each year across the United States. The pitch is always the same: fast, seamless, and often described as "free." But free is rarely the full story.
At ITOnlinePay, we reviewed the fee structures of the most widely used payment platforms and examined how state-level financial regulations — or the absence thereof — shape what consumers actually pay. The findings are instructive, and in some cases, genuinely surprising.
The Illusion of the Free Transfer
Most payment apps advertise zero-cost transfers, and technically, they are not lying. Sending money from a linked bank account to another user is typically free on platforms like Venmo, Zelle, and Cash App. The fees appear the moment you deviate from that baseline.
Instant transfers are among the most common cost drivers. Venmo charges 1.75% (minimum $0.25, maximum $25) to move funds instantly to a debit card or bank account. Cash App charges 1.5% for instant deposits, with a $0.25 floor. PayPal's instant transfer fee sits at 1.75% as well, capped at $25. For someone regularly moving $500 at a time, these charges add up to roughly $8.75 per transaction — or more than $100 annually if the habit is weekly.
Credit card funding is another hidden escalator. Using a credit card to send money through Venmo or Cash App triggers a 3% fee. That charge is not a penalty — it is a deliberate pricing mechanism that offsets interchange costs the platforms absorb. Consumers who fund peer-to-peer transfers with credit cards without understanding this structure are effectively paying a premium on every transaction.
How State Regulations Create Unequal Costs
Here is where the picture becomes more complex. Payment apps operate under a patchwork of state money transmission laws, and the regulatory environment in each state directly influences what platforms charge — and what disclosures they are required to make.
New York maintains some of the most rigorous oversight through the Department of Financial Services (NYDFS). Companies operating in New York must hold a BitLicense or money transmitter license and are subject to strict consumer protection requirements. The result is greater transparency, but compliance costs that some platforms pass through to users in the form of slightly elevated service fees on premium features.
California enforces its Money Transmission Act with particular attention to consumer disclosures. Platforms operating in the state must clearly itemize fees before a transaction is completed. Californians are, in theory, better positioned to make informed decisions — yet the state's high cost of living means that percentage-based fees hit residents proportionally harder.
Texas applies a lighter regulatory touch. While money transmitter licensing is required, ongoing oversight is less intensive. Consumers in Texas may encounter fewer mandatory disclosures, which means fee structures buried in terms of service documents are less likely to be surfaced proactively.
Florida, Georgia, and Ohio fall into a middle tier — licensing requirements exist, but enforcement resources are limited. Consumers in these states bear a greater responsibility to audit their own transaction histories for unexpected charges.
States with no dedicated fintech oversight frameworks — including several in the Mountain West — offer the least structural protection. In these markets, the burden of fee awareness falls almost entirely on the individual user.
Platform-by-Platform Fee Snapshot
To give readers a clearer picture, here is a summary of key charges across the leading platforms as of 2024:
| Platform | Standard Transfer | Instant Transfer Fee | Credit Card Funding | Business Transaction Fee |
|---|---|---|---|---|
| Venmo | Free | 1.75% (min $0.25) | 3% | 1.9% + $0.10 |
| PayPal | Free (bank) | 1.75% (max $25) | 2.9% + fixed fee | 3.49% + fixed fee |
| Cash App | Free | 1.5% (min $0.25) | 3% | 2.75% |
| Zelle | Free | N/A | N/A | Varies by bank |
| Apple Pay | Free (Wallet) | N/A | Varies by issuer | N/A |
| Google Pay | Free | N/A | Varies by issuer | N/A |
Zelle is notably different in that it does not charge end users directly — costs are absorbed by the participating financial institutions. However, if your bank is not a Zelle partner, you may face limitations or be routed through a third-party interface that introduces its own fee structure.
Business Users Face a Different Calculus
For freelancers, small business owners, and gig economy workers, payment app fees carry significantly more financial weight. A graphic designer in Chicago invoicing $2,000 through PayPal's business payment option will pay approximately $72.80 in processing fees on that single transaction. Over the course of a year, those costs can rival — or exceed — the price of a dedicated merchant services account.
Business users in states with robust small business financial literacy programs (California and New York, notably) are more likely to be aware of alternatives, including ACH transfers, dedicated payment processors like Stripe or Square, and bank-direct invoicing solutions that carry lower per-transaction costs.
Practical Steps to Reduce What You Pay
Regardless of your state, there are concrete strategies for minimizing digital wallet fees:
- Use standard transfers whenever timing allows. If the payment is not time-sensitive, the 1–3 business day standard transfer is almost always free.
- Link a bank account, not a credit card. Funding transactions through a debit account or bank balance eliminates the credit card surcharge.
- Review your transaction history monthly. Many consumers do not realize they have been opting into instant transfers by default through auto-settings.
- Consider Zelle for bank-to-bank transfers. For users whose banks support Zelle natively, it remains the cleanest zero-fee option for domestic transfers.
- Evaluate business payment platforms separately. If you receive regular payments professionally, a dedicated merchant processor will likely offer better rates than a consumer-facing app.
- Check your state's money transmitter registry. Most state banking departments publish licensed operators online. If a platform you use is not listed, that is a red flag worth investigating.
The Smarter Path Forward
The digital payments ecosystem is not designed to obscure fees — but it is not designed to highlight them either. Convenience is the product, and convenience carries a cost that varies by platform, transaction type, and, increasingly, by zip code.
Making smarter payment decisions begins with understanding that the regulatory landscape you live in shapes your consumer rights as much as any app's terms of service. Whether you are in a high-oversight state like New York or a lighter-touch environment like Montana, the responsibility to read the fine print remains yours.
At ITOnlinePay, we believe that informed consumers make better financial decisions. Knowing what your payment app is actually charging — and why — is the first step toward keeping your digital financial life as efficient as the technology promises to be.